Dollar Sliding At Start of Busy Week
US Midterms This Week
The US Dollar is down sharply through early European trading on Monday as traders brace for a busy week in the markets. The US midterms tomorrow, RBA rate decision, Eurozone CPI, BOE rate decision and the US NFP release will all take place this week, alongside a slew of Fed speakers, creating plenty of room for volatility. The market is currently pricing in around a 75% chance of a hike by year end, down from 95% at the peak a few weeks ago. Strong US data has been the main driver of the hawkish camp while the recent market turmoil we’ve seen amidst the rout in AI stocks is presenting a strong argument against further Fed tightening.
US/Iran Fears
On the geopolitical front, the main risks look tied to the prospect of Trump launching a fresh offensive against Iran once the midterms are concluded. In this scenario, oil prices will push sharply higher, taking USD higher also. However, the fear around AI stocks remains a key threat to USD and any development in that narrative could cap the upside reaction in USD. As such, we could see choppy, erratic price action this week into the NFP on Friday. In light of strong inflation and GDP data, any upside in Friday’s data should revive hawkish expectations for December. However, any downside surprise could see USD unwind as December rate hike pricing falls back to around 50%.
Technical Views
DXY
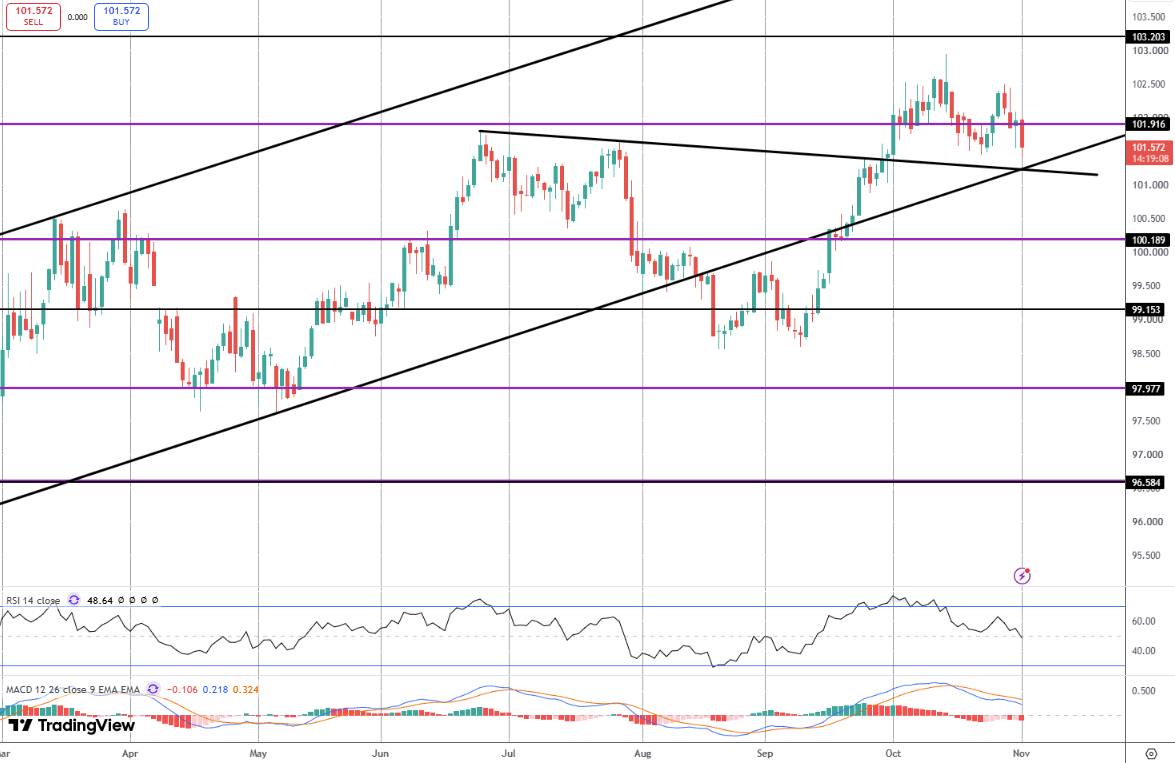
The index has retreated below the 101.91 level again and is now retesting the cradle of support formed at the retest of the broken bear trend line and the bull channel lows. If we slip below this level 100.18 is the next big structural zone to watch. If we bounce from here, focus is back on 103.20 as next bull target.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
With 10 years of experience as a private trader and professional market analyst under his belt, James has carved out an impressive industry reputation. Able to both dissect and explain the key fundamental developments in the market, he communicates their importance and relevance in a succinct and straight forward manner.